Minerals Are the New Oil: The Hidden Resource War Threatening American Dominance
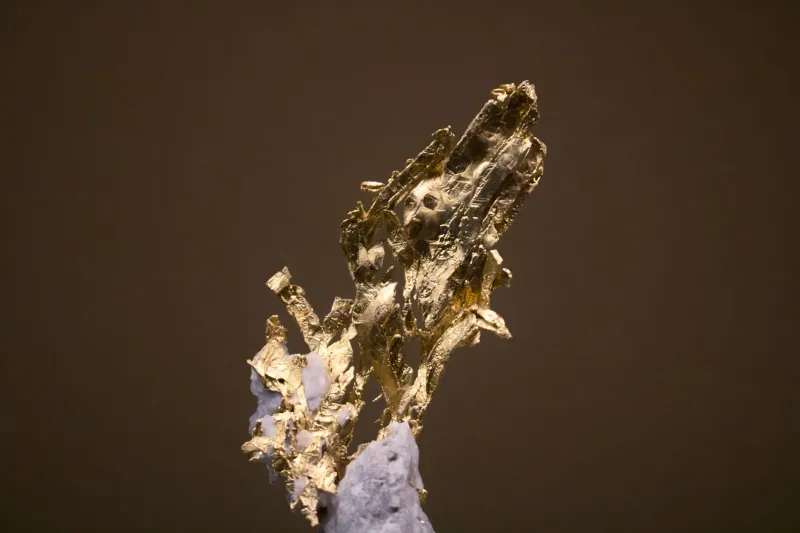
For most of the twentieth century, geopolitical power was measured in barrels. Nations that controlled oil controlled economies, armies, and the destinies of governments that depended on them. That calculus has not disappeared — but it has evolved in ways that Washington has been painfully slow to fully reckon with. Today, a new class of materials — rare earth elements, lithium, cobalt, and nickel among them — has quietly assumed the strategic significance once reserved for crude oil. And by nearly every meaningful metric, the United States is losing the competition to secure them.
The numbers are stark. China currently controls more than 80 percent of global rare earth processing capacity. It dominates the refining of cobalt sourced from the Democratic Republic of Congo. It has invested aggressively in lithium extraction across South America's so-called Lithium Triangle — Argentina, Bolivia, and Chile — while American policymakers were still debating the merits of the energy transition itself. This is not an accident of geography or geology. It is the product of decades of deliberate industrial strategy, patient diplomacy, and state-backed capital deployed with a precision that free-market orthodoxy in Washington was structurally ill-equipped to match.
What Makes These Minerals Different
To understand why this matters, one must first understand what these materials actually do. Rare earth elements — a group of seventeen metallic elements including neodymium, dysprosium, and terbium — are essential components in the permanent magnets that drive electric vehicle motors, wind turbines, and advanced weapons systems including guided missiles, radar arrays, and jet engines. Lithium and cobalt are the foundational inputs for the battery technology that powers everything from smartphones to F-35 fighter jets. Without reliable access to these materials, the United States cannot manufacture the technologies it has staked both its green economy and its military edge upon.
This creates a paradox that deserves far more attention than it receives in mainstream policy discourse. The very energy transition that Washington has championed as a pathway to reducing dependence on fossil fuels — and by extension, on petrostates with adversarial interests — is generating an entirely new category of strategic vulnerability. Solar panels require silver and tellurium. Wind turbines demand rare earth magnets. Electric vehicles consume lithium, cobalt, nickel, and manganese. The more aggressively the United States pursues decarbonization, the deeper its exposure to supply chains that Beijing has already worked to dominate.
China's Long Game
China's position in this arena was not built overnight. Beginning in earnest in the 1990s under the guidance of Deng Xiaoping — who reportedly remarked that "the Middle East has oil; China has rare earths" — Beijing pursued a systematic strategy of developing domestic mining capacity, subsidizing processing infrastructure, and acquiring stakes in foreign mineral assets. When the rest of the world was largely indifferent to rare earths, Chinese state enterprises were building the industrial ecosystem to refine them at scale.
By the time Western governments began paying serious attention — roughly around 2010, when China temporarily restricted rare earth exports to Japan during a territorial dispute — the structural advantages Beijing had accumulated were already formidable. Processing technology, trained workforces, environmental permitting frameworks calibrated to tolerate the considerable pollution involved in mineral refining — all of these had been quietly assembled while Washington focused elsewhere.
Today, China's leverage is not merely theoretical. A sustained disruption to Chinese rare earth exports would cascade through American defense procurement within months. The Pentagon has acknowledged this vulnerability in successive reports, yet the gap between acknowledgment and remediation remains wide.
The Scramble for Alternatives
The United States is not without options, and the past several years have seen genuine — if belated — efforts to construct alternative supply chains. The Inflation Reduction Act of 2022 included provisions designed to incentivize domestic battery manufacturing and reward automakers for sourcing minerals from allied nations. The Biden administration invoked the Defense Production Act to accelerate domestic critical mineral projects. The CHIPS and Science Act, while primarily focused on semiconductors, reflected a broader awakening to the dangers of concentrated foreign supply chains.
Several nations are positioning themselves as credible alternative suppliers. Australia, which holds significant deposits of lithium and rare earths, has deepened its partnership with Washington under the AUKUS security framework, and its mining sector has attracted substantial American and allied investment. Canada, home to substantial reserves of cobalt, nickel, and lithium, has similarly aligned with U.S. supply chain diversification goals. The two governments formalized a joint action plan on critical minerals in 2023, a development that received less attention than it warranted.
In Africa, the competition is particularly acute. The Democratic Republic of Congo holds an estimated 70 percent of the world's cobalt reserves, and both Washington and Beijing have recognized its pivotal importance. Chinese firms currently hold dominant positions in Congolese mining operations, but the United States has moved to challenge that dominance through the Lobito Corridor rail project — a major infrastructure investment designed to link mineral-rich regions of the DRC, Zambia, and Angola to Atlantic ports, creating an export pathway outside Chinese-controlled logistics networks.
Zambia, Zimbabwe, and Mozambique have all emerged as targets of intensified American diplomatic and investment attention. Yet analysts familiar with the region caution that the United States remains years behind China in terms of on-the-ground relationships, infrastructure commitments, and the sheer volume of capital deployed.
The Military Dimension
Perhaps the most underappreciated dimension of this contest is its direct implications for American military capability. The Department of Defense has identified over a dozen critical minerals for which the United States is entirely import-dependent, with China as the primary or sole supplier for several of them. Neodymium-iron-boron magnets, essential for precision-guided munitions and advanced aircraft systems, flow predominantly through Chinese processing facilities. Samarium-cobalt magnets, used in high-performance military applications requiring heat resistance, present similar vulnerabilities.
In a scenario involving direct military confrontation with China — or even a sustained period of severe diplomatic tension — these dependencies could translate into genuine operational constraints for American forces. Defense planners have begun modeling such scenarios with increasing urgency, and the conclusions are uncomfortable. Stockpiling provides a partial buffer, but not an indefinite one. Domestic processing capacity, where it exists at all, remains a fraction of what would be required to sustain wartime production.
A Structural Problem Demanding Structural Solutions
The challenge the United States faces in critical minerals is not amenable to quick fixes or singular policy interventions. It reflects a structural mismatch between the long time horizons required to develop mining and processing infrastructure — often a decade or more from exploration to production — and the short electoral cycles that shape American political attention. Private capital, absent strong policy signals and risk-sharing mechanisms from government, has historically been reluctant to commit to projects with such extended payback periods.
What is required is a sustained, bipartisan commitment to treating critical mineral security with the same seriousness that successive administrations have applied to oil security — combined with a willingness to work through multilateral frameworks, allied partnerships, and, where necessary, direct government investment. The model of passive reliance on market forces to sort out supply chains of profound national security consequence has been tested and found wanting.
The coming decade will reveal whether Washington has genuinely internalized that lesson, or whether the recognition of vulnerability will once again outpace the political will to address it. In a contest where Beijing has been playing the long game for thirty years, the margin for continued complacency is vanishingly thin.